Home / Research / Restatements (8-K Item 4.02)
Published 2026-10-19 · updated 2026-10-19 · RedFlagFilings research · 2,605 verified flags from SEC filings, 2015-01-09 to 2026-10-16
Historical averages, not a prediction, a trading strategy or investment advice. Many flagged stocks went up.
An 8-K under Item 4.02 ("non-reliance") tells investors that previously issued financial statements, or the auditor's report on them, should no longer be relied upon because of an error. It usually leads to a restatement of the affected periods.
We separate a company's first notice that its financial statements are wrong from follow-up or repeat filings about a non-reliance already announced and from narrower notices (only the auditor's report withdrawn, or only internal-control conclusions).
| Group | 90 days after the filing | 180 days after the filing | 1 year after the filing | |||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| n | median return | mean return* | median vs SPY | mean vs SPY* | % trailed SPY | n | median return | mean return* | median vs SPY | mean vs SPY* | % trailed SPY | n | median return | mean return* | median vs SPY | mean vs SPY* | % trailed SPY | |
| All restatement / non-reliance notices 2,605 flags | 1,959 | -0.6% | -7.8% | -6.2% | -9.6% | 59% | 1,887 | -0.5% | -10.9% | -10.4% | -13.8% | 59% | 1,713 | -9.7% | -21.6% | -23.9% | -27.4% | 61% |
| First notice: financial statements can't be relied on 2,566 flags | 1,933 | -0.6% | -7.8% | -6.1% | -9.6% | 59% | 1,861 | -0.5% | -10.9% | -10.3% | -13.7% | 59% | 1,690 | -10.1% | -21.9% | -23.9% | -27.6% | 61% |
| Follow-up, repeat or narrower notice 39 flags | 26 | fewer than 30 completed windows | 26 | fewer than 30 completed windows | 23 | fewer than 30 completed windows | ||||||||||||
* Mean = trimmed mean that drops the top and bottom 5% of returns (a few micro-cap returns of +1,000% or more would otherwise dominate). "vs SPY" is the stock's return minus the S&P 500 ETF's return over the same dates, in percentage points.
| Year | Flags | 90 days | 180 days | 1 year | ||||||
|---|---|---|---|---|---|---|---|---|---|---|
| n | median vs SPY | % trailed | n | median vs SPY | % trailed | n | median vs SPY | % trailed | ||
| 2015 | 197 | 94 | -11.0% | 71% | 93 | -19.5% | 70% | 92 | -35.5% | 65% |
| 2016 | 160 | 85 | -3.5% | 52% | 85 | -6.0% | 55% | 85 | -15.0% | 61% |
| 2017 | 131 | 77 | -14.2% | 69% | 77 | -14.0% | 73% | 76 | -26.6% | 72% |
| 2018 | 126 | 74 | -13.4% | 72% | 74 | -24.9% | 77% | 74 | -49.5% | 88% |
| 2019 | 93 | 54 | -14.5% | 72% | 54 | -28.0% | 81% | 53 | -39.0% | 79% |
| 2020 | 89 | 70 | -0.9% | 53% | 70 | -0.5% | 50% | 69 | +16.8% | 43% |
| 2021 | 838 | 719 | -0.8% | 51% | 694 | +0.8% | 49% | 629 | +3.7% | 42% |
| 2022 | 286 | 236 | +2.1% | 44% | 230 | +2.9% | 45% | 187 | -26.2% | 65% |
| 2023 | 236 | 181 | -14.3% | 76% | 176 | -26.6% | 74% | 166 | -63.0% | 83% |
| 2024 | 234 | 199 | -16.1% | 71% | 193 | -25.6% | 75% | 183 | -46.4% | 75% |
| 2025 | 129 | 116 | -12.0% | 66% | 113 | -16.2% | 66% | 99 | -42.9% | 74% |
| 2026 | 86 | 54 | -16.4% | 70% | 28 | too few | 0 | too few | ||
Recent years have fewer completed windows: a 1-year return needs a full year after the filing.
| Market cap at the flag | 90 days after the filing | 180 days after the filing | 1 year after the filing | |||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| n | median return | mean return* | median vs SPY | mean vs SPY* | % trailed SPY | n | median return | mean return* | median vs SPY | mean vs SPY* | % trailed SPY | n | median return | mean return* | median vs SPY | mean vs SPY* | % trailed SPY | |
| Nano-cap (under $50M) 551 flags | 523 | -11.3% | -12.5% | -15.7% | -16.1% | 69% | 496 | -20.8% | -17.8% | -26.0% | -24.0% | 71% | 471 | -35.7% | -25.0% | -51.5% | -38.1% | 72% |
| Micro-cap ($50M-300M) 673 flags | 644 | -0.3% | -5.8% | -3.3% | -6.8% | 55% | 619 | +0.2% | -7.5% | -3.9% | -8.8% | 53% | 546 | +0.5% | -14.2% | -2.3% | -18.0% | 51% |
| Small-cap ($300M-2B) 570 flags | 555 | -0.3% | -5.9% | -3.8% | -6.8% | 54% | 540 | +0.0% | -7.1% | -4.5% | -8.2% | 53% | 482 | -2.5% | -20.1% | -8.8% | -21.1% | 55% |
| Mid-cap ($2B-10B) 91 flags | 90 | +0.3% | +0.9% | -5.7% | -3.6% | 54% | 86 | +3.2% | +1.9% | -2.3% | -7.2% | 55% | 81 | +1.6% | -3.8% | -11.6% | -14.9% | 63% |
| Large-cap (over $10B) 24 flags | 24 | fewer than 30 completed windows | 23 | fewer than 30 completed windows | 22 | fewer than 30 completed windows | ||||||||||||
| Market cap unknown at the flag 696 flags | 123 | -1.2% | -11.5% | -7.6% | -13.0% | 67% | 123 | -19.8% | -22.6% | -25.0% | -25.0% | 72% | 111 | -61.9% | -54.2% | -68.0% | -57.0% | 82% |
* Mean = trimmed mean that drops the top and bottom 5% of returns (a few micro-cap returns of +1,000% or more would otherwise dominate). "vs SPY" is the stock's return minus the S&P 500 ETF's return over the same dates, in percentage points.
| Group | 90 days | 180 days | 1 year | |||
|---|---|---|---|---|---|---|
| completed windows | delisting-adjusted | completed windows | delisting-adjusted | completed windows | delisting-adjusted | |
| All restatement / non-reliance notices | -6.2% | -6.1% (39 stopped) | -10.4% | -10.1% (78 stopped) | -23.9% | -14.5% (204 stopped) |
| First notice: financial statements can't be relied on | -6.1% | -6.1% (38 stopped) | -10.3% | -10.1% (77 stopped) | -23.9% | -14.5% (201 stopped) |
| Follow-up, repeat or narrower notice | n/a | n/a (1 stopped) | n/a | n/a (1 stopped) | n/a | n/a (3 stopped) |
Median return vs SPY. The plain figure only counts stocks that still traded at the end of the window. The delisting-adjusted figure also counts stocks that stopped trading first at their last close. Stopping can mean a delisting or bankruptcy, but also an acquisition, merger or going-private deal, and a last close can come before a later loss (for example shares that keep trading over the counter without price data), so the adjustment can move the median either way. Companies that no longer have any ticker are missing from both figures.
The 2021 SPAC wave: 838 of these notices were filed in 2021, 535 of them by companies the SEC classifies as blank checks (industry code 6770). Most were SPACs correcting how they accounted for warrants and redeemable shares after an SEC staff statement that April. Many SPACs later liquidated or merged and stopped trading close to their trust value, which is why counting stocks that stopped trading makes the restatement figures less negative here, unlike for the other flag types.
| Filed | Company | Flag | Market cap at the flag | 90 days vs SPY | 1 year vs SPY |
|---|---|---|---|---|---|
| 2020-02-26 | CROWN CASTLE INTERNATIONAL CORP (CCI) | Non-reliance / restatement | $68B | +2.4% | -23.6% |
| 2016-01-13 | SIMON PROPERTY GROUP INC /DE/ (SPG) | Non-reliance / restatement | $57B | +6.3% | -17.4% |
| 2026-02-27 | MONOLITHIC POWER SYSTEMS INC (MPWR) | Non-reliance / restatement | $56B | +28.9% | pending |
| 2025-05-07 | AXON ENTERPRISE, INC. (AXON) | Non-reliance / restatement | $47B | +31.4% | -61.5% |
| 2020-02-13 | BAXTER INTERNATIONAL INC (BAX) | Non-reliance / restatement | $47B | +9.9% | -31.5% |
| 2024-11-25 | Discover Financial Services (DFS) | Non-reliance / restatement | $46B | +7.5% | n/a |
| 2019-05-06 | Kraft Heinz Co (KHC) | Non-reliance / restatement | $40B | +0.9% | -5.1% |
| 2021-02-24 | PIONEER NATURAL RESOURCES CO (PXD) | Non-reliance / restatement | $32B | -5.8% | +50.0% |
| 2022-01-26 | STANLEY BLACK & DECKER, INC. (SWK) | Non-reliance / restatement | $27B | -17.6% | -45.4% |
| 2018-06-28 | PPG INDUSTRIES INC (PPG) | Non-reliance / restatement | $26B | -2.6% | +2.0% |
| 2024-11-05 | Archer-Daniels-Midland Co (ADM) | Non-reliance / restatement | $25B | -14.0% | -14.5% |
| 2021-03-16 | PLUG POWER INC (PLUG) | Non-reliance / restatement | $22B | -41.8% | -59.7% |
Every flag in this group where the company was worth at least $10B on the filing date and its stock traded at least $25M a day (one row per company, its latest such flag, largest first). Big companies are rare in this data and are shown for context, not as a sample.
Download the numbers on this page: restatements.csv · Chart image: cards/restatements.png · Recent flags of this type: Restatements
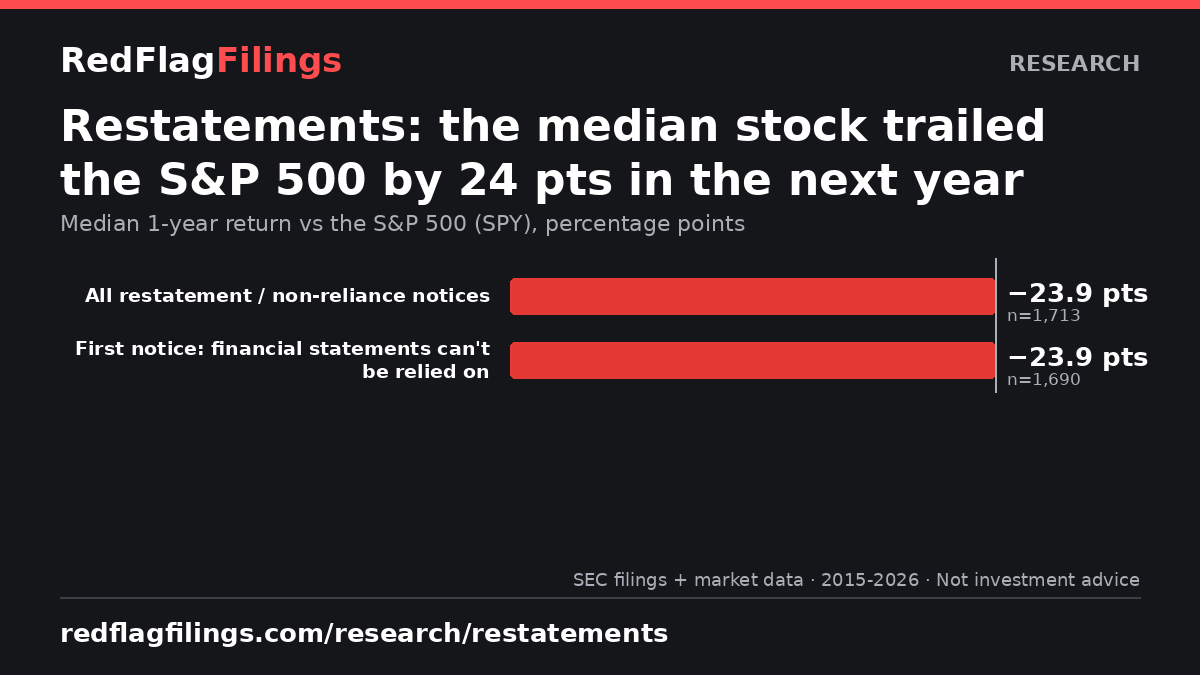
Restatements (8-K Item 4.02): across 1,713 flags with a full year of price data (2015-2026), the median stock returned -9.7% and trailed the S&P 500 (SPY) by 23.9 percentage points over the next year; 61% did worse than SPY.
First notice: financial statements can't be relied on: median 1-year return vs SPY -23.9%, 61% trailed SPY (n=1,690). 204 of these stocks stopped trading within a year; counting them at their last trade moves the 1-year median vs SPY from -23.9% to -14.5%.
204 of these stocks stopped trading within a year; counting them at their last trade moves the 1-year median vs SPY from -23.9% to -14.5%.
Nano caps (under $50M at the flag) had a median 1-year return vs SPY of -51.5% (n=471); there are too few large-cap cases for a reliable figure.
No. These are historical averages computed from SEC filings and market data. They are not a prediction or a recommendation to buy or sell any security, and many flagged stocks went up.
The week's most serious auditor changes, restatements, late filings and going-concern warnings, in plain English. Free. Unsubscribe anytime.
Subscribe to the newsletter →
The signup form didn't load here (often an ad or privacy blocker). This opens beehiiv's secure signup page.
Form not showing? Subscribe on beehiiv →
Newsletter delivered by beehiiv. See our privacy policy.